Medicare Part D.Prescription Drug Coverage.
Part D helps cover prescription medications — but the right plan depends on your actual drug list, dosage, pharmacy, plan formulary, tiers, restrictions, and yearly changes. We help you check the details before you choose or renew.
- Medication List ReviewedWe start with the prescriptions you actually take.
- Pharmacy CheckedPreferred pharmacies can affect your costs.
- Year-Round HelpPlans and formularies can change every year.
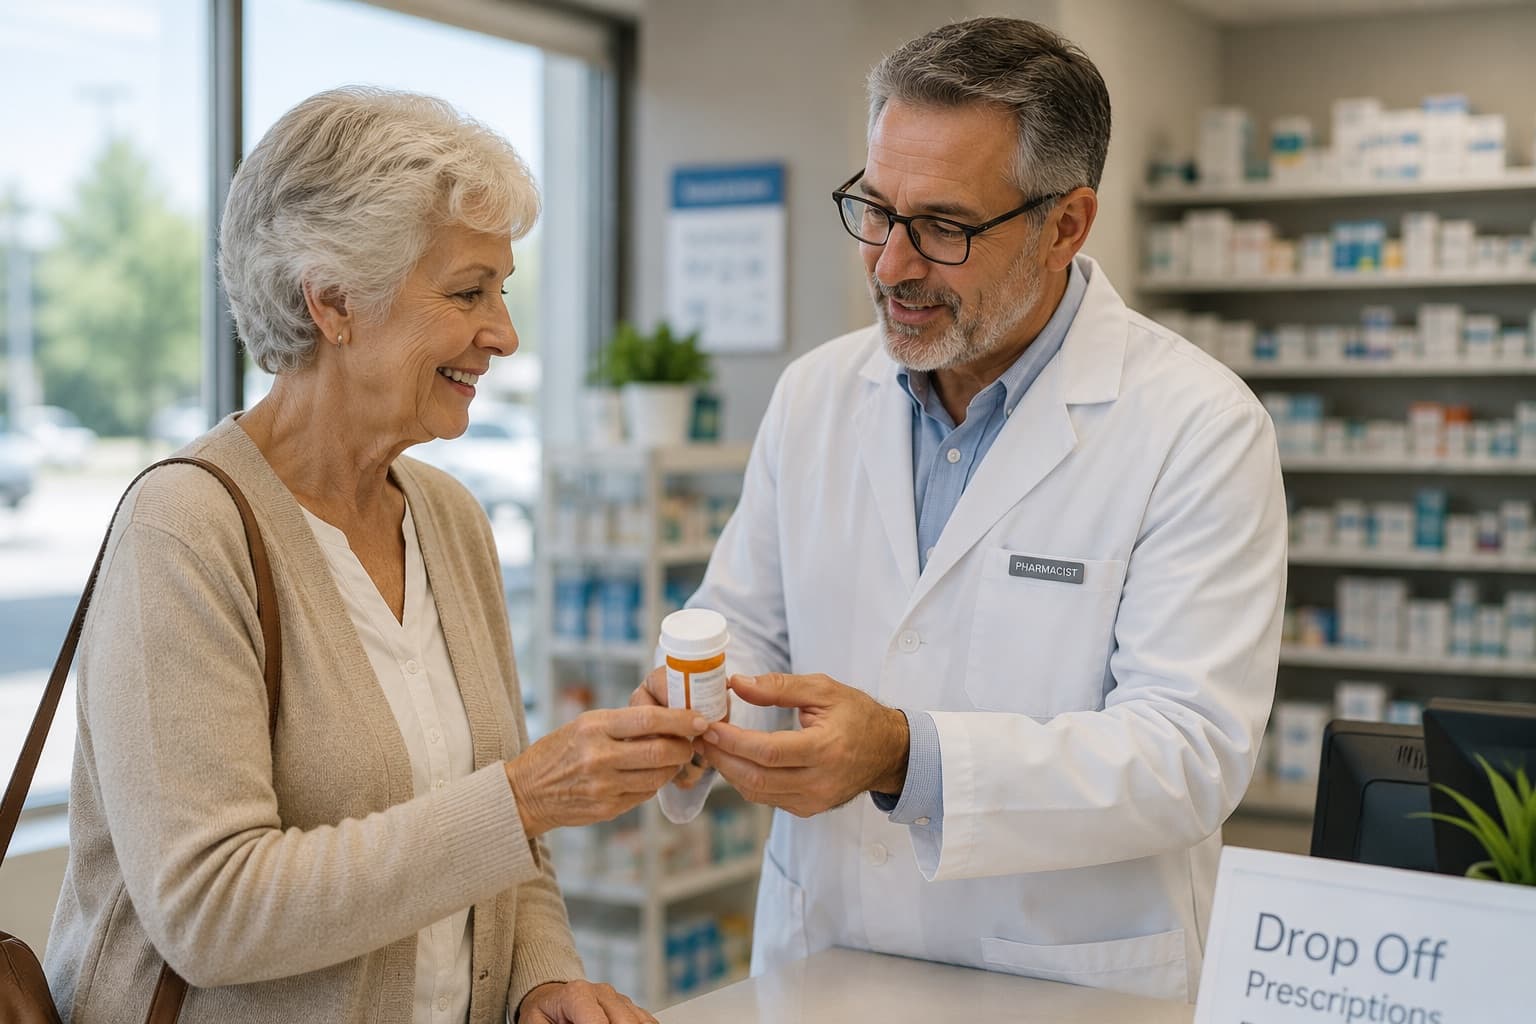
What We Check Before You Choose
Annual review matters — plans and formularies can change every year, so the right fit can change too.
How Prescription Drug Coverage Works
Part D plans cover medications through a formulary. What you pay can depend on the plan, the drug tier, your pharmacy, deductibles, restrictions, and where you are in the plan year.
Your Medication List
The drugs, doses & quantities you take.
The Plan Formulary
Each plan’s own list of covered drugs.
Drug Tier
01Where each medication sits can change your copay or coinsurance.
Preferred Pharmacy
02Using a preferred pharmacy may lower costs with some plans.
Deductible & Copays
03Plans may include a premium, a deductible, copays, or coinsurance.
Prior Auth / Step Therapy
04Some drugs have rules to meet before they’re covered.
Coverage Phases
05What you pay can shift during the year as spending adds up.
Annual Changes
06Formularies, pharmacies, and costs can change each year.
Coverage and cost can vary by plan, pharmacy, and medication — and the right plan depends on the drugs you take.
The Details We Check Before You Enroll
A Part D review starts with the exact list of medications you take — then runs each one through the details that decide what a plan actually costs you.
Your Medication List
Every review begins here. Before comparing any plan, we build the real list of what you take — because the plan that looks cheapest on paper can change once your medications are entered.
Why it matters: small medication details can create large cost differences between plans.
Medication Name
Brand or generic — the exact drug matters for coverage.
Dosage & Quantity
Strength and amount can affect tier and cost.
How Often You Take It
Frequency changes what you’ll use over the year.
Preferred Pharmacy
Where you fill can change what a plan charges.
Mail-Order Preference
Some plans price 90-day mail-order differently.
Generic Alternatives
A lower-tier equivalent may reduce cost.
Restrictions / Prior Authorization
Check firstPrior auth, step therapy, or quantity limits may apply.
What Can Change What You Pay
Part D costs aren’t based only on the monthly premium. Formularies, tiers, deductibles, pharmacies, and coverage phases can all affect your total.
The lowest premium is not always the lowest total cost.
Monthly Premium
The premium is only one part of the total cost — not the whole picture.
Deductible
Some plans may have a deductible before certain drug costs are reduced.
Drug Tier
Your medication’s tier can change the copay or coinsurance you pay.
Preferred Pharmacy
Using a preferred pharmacy may lower costs with some plans.
Coverage Phases
Your costs can change during the year depending on prescription spending.
Out-of-Pocket Costs
A plan that looks cheaper at first may not be lowest once medications are checked.
Worth remembering: Don’t choose a Part D plan by premium alone. The lowest premium can cost more once your medications are entered.
Your Drug Plan Can Change Every Year
Even if you keep the same plan, the way your drugs are covered can change next year. Here’s what to look at when you review.
Coverage can shift even if you keep the same plan
Each fall, plans reset their formularies, networks, and costs. The plan that fit your medications this year may treat them differently in January.
Covered as it is today
May be covered differently
That’s why an annual review helps — it confirms your plan still fits the drugs you actually take.
Formulary
What sits on the covered-drug list can shift.
- Formulary changes
- New medication added
Cost & Tiers
Where a drug sits can move your copay.
- Tier changes
- Premium / deductible changes
Pharmacy
Preferred & mail-order networks can change.
- Pharmacy network changes
- Mail-order pricing
Coverage Rules
Check firstRules to meet before a drug is covered.
- Prior authorization
- Step therapy
- Quantity limits
Why an annual look helps
A drug covered this year may not be covered the same way next year — the tier, the pharmacy, or the rules around it can shift even if you keep the same plan.
Questions People Ask Before Choosing a Drug Plan
These are the Part D questions that matter before you enroll, renew, change medications, or assume your current plan still fits.
It can still be worth considering. If you delay drug coverage without other creditable coverage, a late-enrollment cost may apply later, and your medication needs can change over time. Whether it fits depends on your situation.
Not necessarily. Each plan has its own formulary — the list of drugs it covers — so a medication may be covered by one plan and not another. Coverage can also depend on the drug’s tier and any restrictions attached to it.
Yes, it can. Many plans have preferred pharmacies, and using one may lower what you pay compared with a standard or out-of-network pharmacy. Mail-order options can also affect cost for some medications.
A formulary is the list of prescription drugs a plan covers. Plans group covered drugs into tiers, and the formulary can change from year to year — which may change what a medication costs even if you keep the same plan.
Tiers are cost groupings a plan uses for covered drugs. Lower tiers often include generics with lower copays, while higher tiers may include brand-name or specialty drugs that can cost more. The same drug can sit on different tiers across plans.
Yes. Formularies, tiers, pharmacy networks, premiums, and deductibles can all change annually. A plan that fit well one year may not fit the same way the next — which is why an annual review can help confirm it still matches your medications.
Depending on your situation, enrolling later without other creditable drug coverage may lead to a late-enrollment cost that can apply for as long as you have Part D. The specifics depend on your circumstances and timing, so it’s worth reviewing before you decide.
Continue Through Medicare Basics
Part D is prescription drug coverage. These guides explain the Medicare pieces around it — follow the path.
Let’s check your prescriptions before you choose.
Get clear answers about formularies, drug tiers, pharmacies, restrictions, costs, and annual plan changes — with a local advocate who’s here year-round.
Talk to a local advocate
Schedule Your 20-Minute Fit Checkor call / text (315) 748-6461